Why are so many data centres located in the highest risk tornado regions?
Data centre footprint is growing in areas with high-severity tornado exposure
 Prefer us on Google


Summary
The economics of data centres in seemingly counterintuitive locations
Tornado Alley and its close cousin Dixie Alley are both popular locations to build data centres, despite the elevated frequency of twisters and windspeeds reaching 200 mph. Why is this?
Our analysis of data centres and tornado events found that 80% of affected floorspace sits in just 20 towns and cities. Which begs the question, why do developers choose to build high-tech infrastructure in those cities?
To analyse the key decision-making factors, we’ve taken a city from each ‘alley’ – Dallas and Atlanta – and compared them with other potential sites. Namely Silicon Valley, New Jersey and Sparks, Nevada.
The scale of the issue
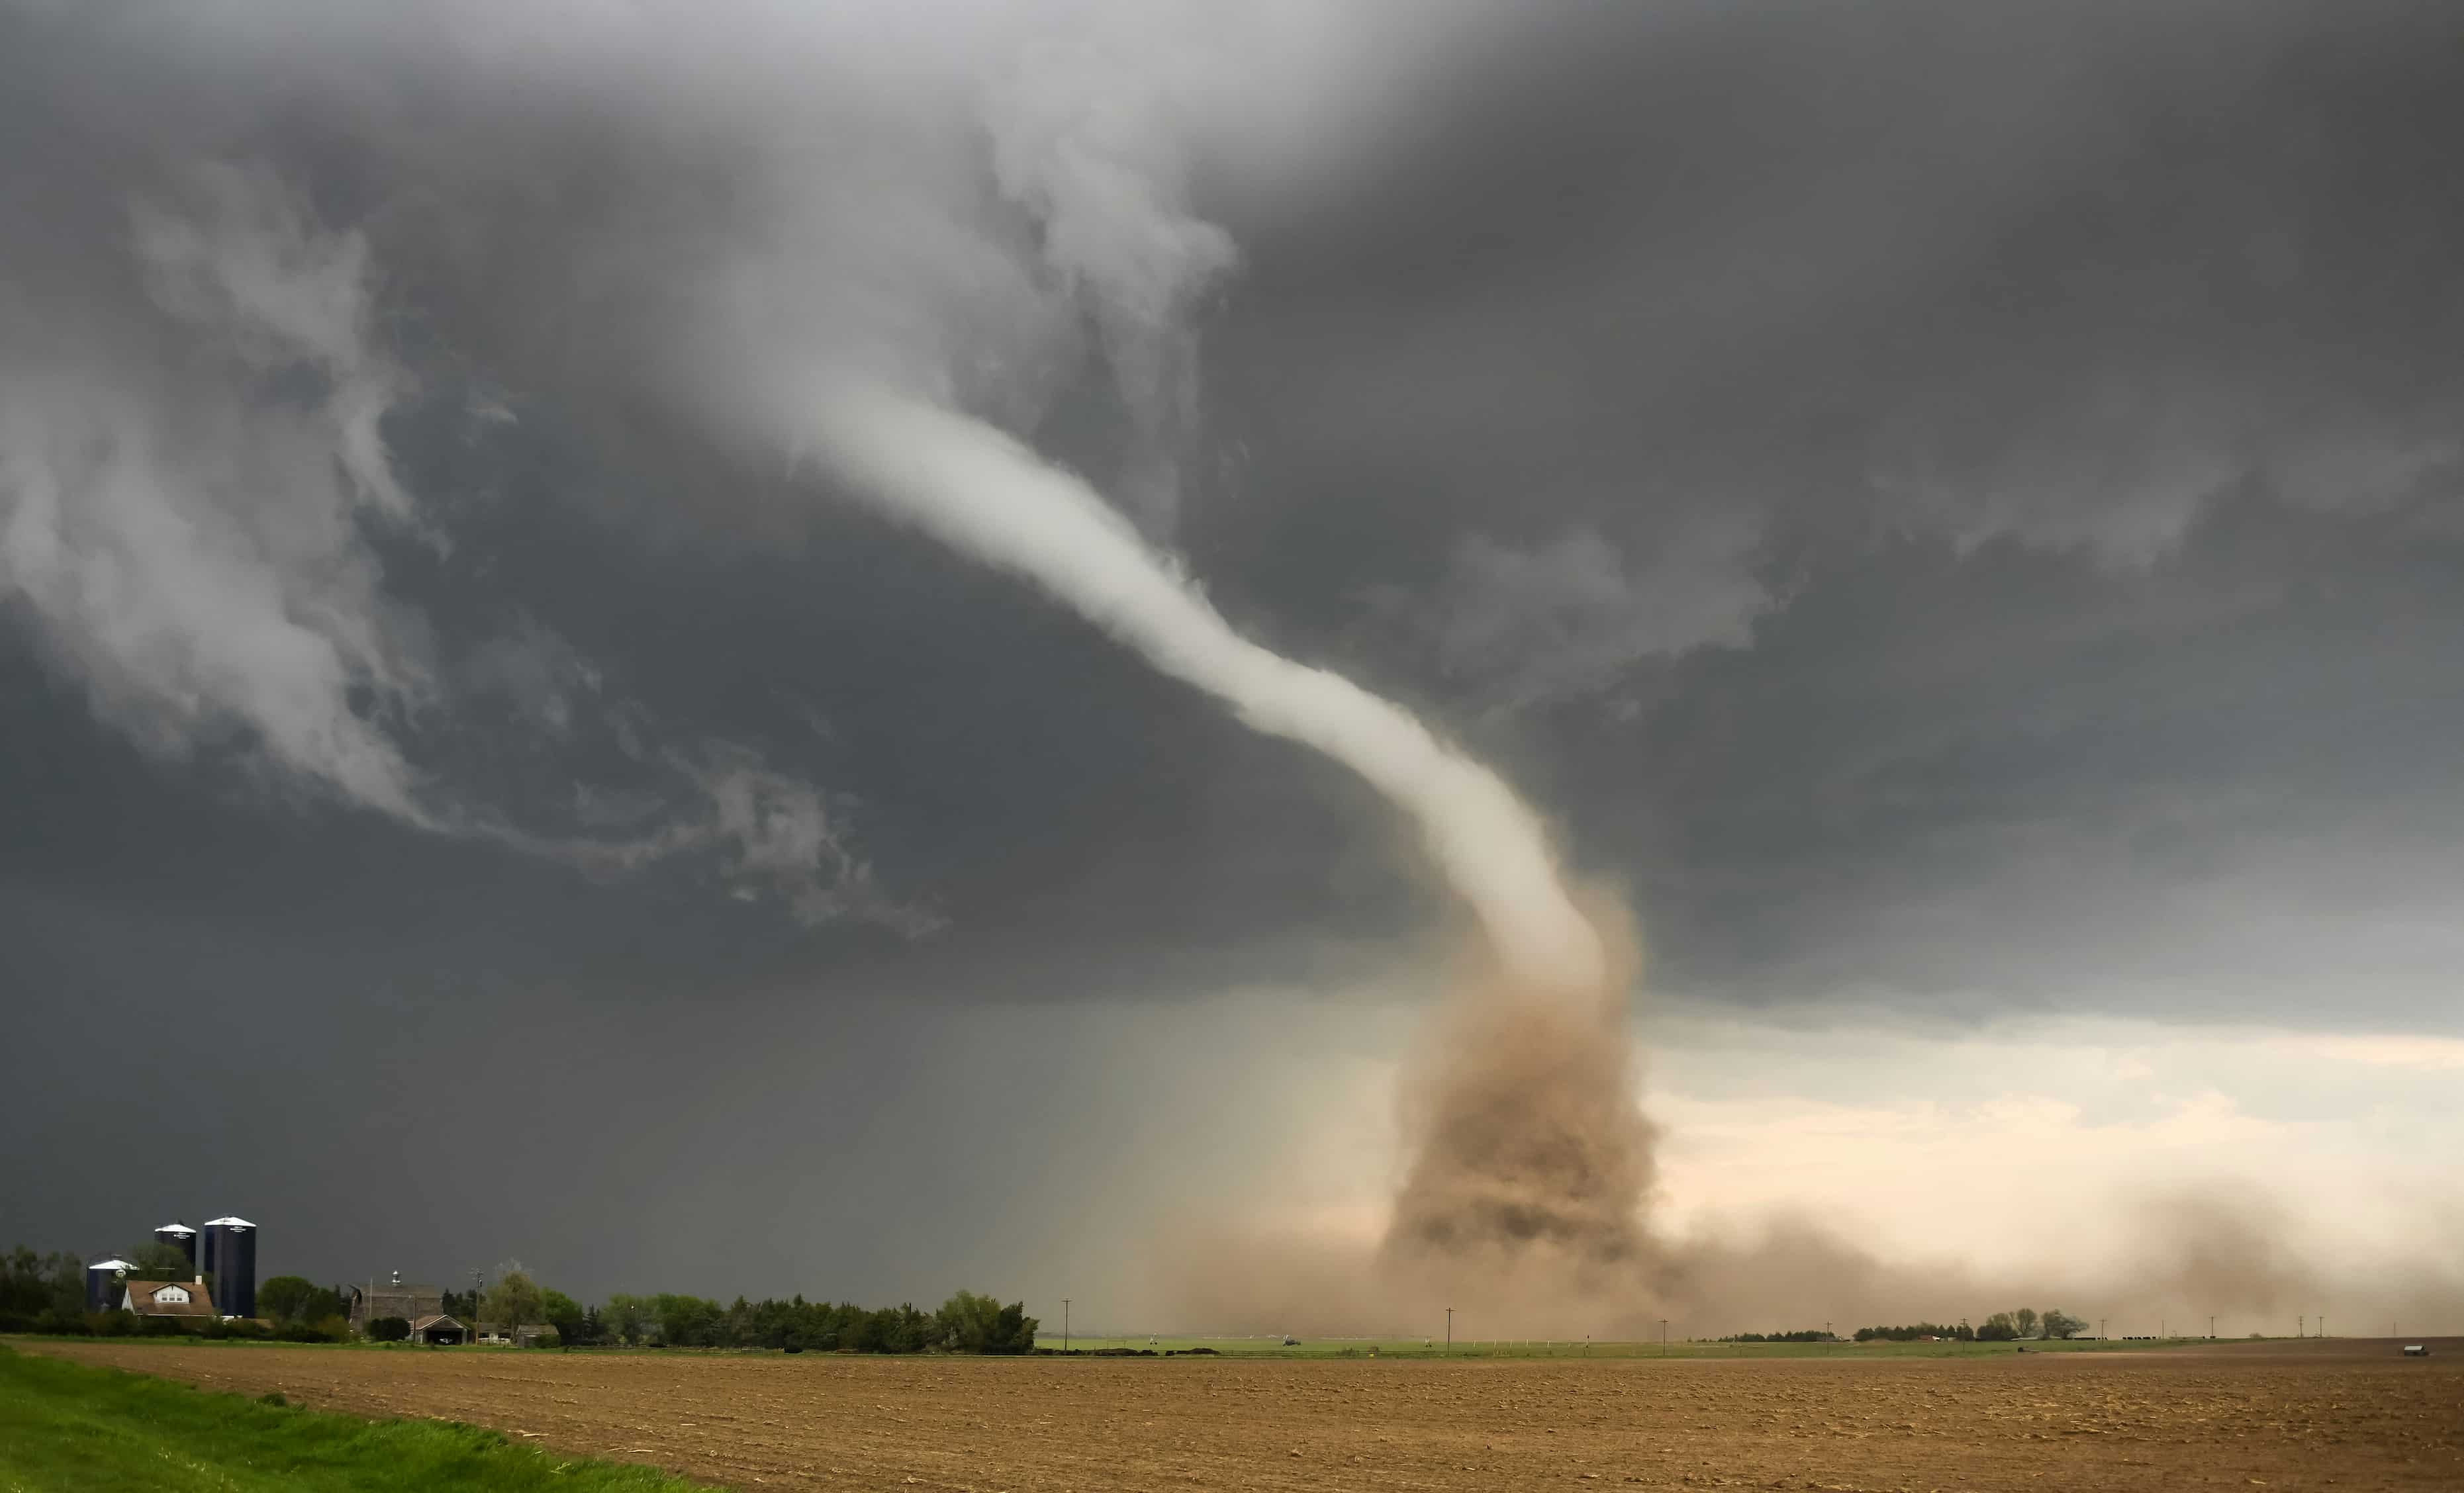
- Tornadoes are a byproduct of supercell thunderstorms, a type of severe convective storm (SCS). Howden RE estimated total US SCS losses in 2024 at $50bn.
- Tornado severity is measured on the Enhanced Fujita (EF) scale. An EF1 can cause ‘moderate’ damage, an EF2 ‘considerable’. EF3 and EF4 are ‘severe’ and ‘devasting’ respectively.
- 81 million square feet of affected data centre floorspace* sits in the 20 highest-risk towns. That’s an area more than 2.5x the size of the City of London, or two Central Parks.
- 32% of US data centres' operational floorspace has been hit by a tornado rated EF1 or greater* in the last ten years.
*Operational and under construction
How does natural disaster risk affect land prices?
It’s reasonable to think that land prices might follow natcat risk, but that's not always the case.
The Federal Emergency Management Agency (FEMA) folds data on tornados into a broader rating system, incorporating other natural disaster threats, such as hurricanes and earthquakes.
Of the counties we studied, median land price per acre varies hugely, with a fivefold swing from $21,000 to $100,000 per acre. Cumberland County in South Jersey** (riskiest) is the cheapest, but Dallas County (second riskiest) is the most expensive. Cheaper sites are available in the Dallas Prairie area ($37,000 per acre). There, land costs are broadly in line with those of the safest overall natcat profile, Sparks, at $39,000 per acre.
**This analysis looks at North and South Jersey differently, as they are quite separate data centre markets. Traditionally, North Jersey has been strategically important, due to its proximity to New York. South Jersey has recently grown in popularity.
The financial trade offs
With low natcat risk and right at the heart of the tech industry, Silicon Valley is the traditional hub for data centres. There, construction costs $13.31 per watt.
According to Turner & Townsend’s benchmark Data Centre Construction Cost Index, Silicon Valley is the world’s fifth most expensive place to build, behind Tokyo, Singapore, Zurich and Osaka. And New Jersey is not far behind, in sixth, costing $12.90 per watt. The rest of our studied cities fall broadly around the $10 per watt range.
Any further costs for data centre target hardening are an economic decision. This is because design provisions for tornados are more likely to appear in negotiations with tenants, off-takers, financiers and insurers than with building inspectors.
Data centres don’t fit neatly into ASCE-7, the American Society of Civil Engineers (ASCE) framework that most local building codes are based on. The rules are based on human impact, rather than financial value. This means data centres are currently exempt from any specific requirements for tornado resilience. It is possible to build them to the levels required of schools and hospitals, but it comes at significant expense. According to Professor Grace Yan, of the University of Missouri and a fellow of the ASCE, the cost difference isn’t as much as you might think. She estimates target hardening that strengthens a data centre to withstand an EF3 (up to 165mph) adds an extra 10% on top of the usual construction costs.
Target hardening can mean a trade-off between higher construction costs and higher insurance costs. For example, insurance around SLA uptime protection cover would be more expensive without substantial tornado-proofing.
Another factor in the financial balancing act is utility costs. These vary massively across the US, with some of the most capacious supply and attractive prices in places with severe tornado risk. Power stations are legally required to be target hardened to withstand the force of 300mph winds, so grid stability in such locations is not a serious issue.
Tax is where it gets really interesting
Effective property taxes in the relevant counties range from 0.52%-2.02%, which is a huge swing. Location decisions are taken with state and county-level incentivisation at the forefront of the process.
Several incentives are in play, including data centre specific tax credits, tax exemption for qualifying projects and locally negotiated PILOT (payment in lieu of taxes) schemes.
Such things are very much locally driven:
- California has no specific data centre incentives. But it does have tax incentives around job creation, investment and R&D that any sector can apply for. A proposal for a data centre sales tax cap was removed from the legislative process in January 2025.
- New Jersey does have a specific data centre tax programme, disbursed over five years. It’s based on a calculation of 0.1% of capital investment multiplied by new jobs, 25% of capital investment, or $250 million, whichever is the lesser. It’s also possible to arrange PILOT schemes over 30 or 35 years.
- Nevada offers a 75% sales / property tax break for data centres. Smaller data centres can get this tax relief for ten years, the largest for 20.
- Texas goes one step further and offers full exemption from state taxes for 10, 15 or 20 years, depending on project size.
- Georgia has a tax abatement programme for data centres around sales and use tax. But many data centres are developed in partnership with county-level local governments, often using a bond lease structure.
How bond lease structure works
The bond lease structure involves a private/public partnership. A local government forms a ‘development authority’, which takes title to the land. It then leases the land back to the developer, taking advantage of tax free status. The developer makes pre-agreed payments for a set amount of time, to be negotiated by the parties involved. Once a bond-lease / PILOT deal has gone through the state’s bond validation process, this forms a legal contract. At that point, it is not subject to political movements in the same way tax breaks are.
Local pushback matters
Across the US, data centres are becoming an increasingly political issue. Concerns about environmental impacts, water use, reporting transparency and passing on costs to everyday consumers have led to many cities taking action. Some of our studied locations have reacted differently than others.
- In 2025, California passed a bill that authorises the California Public Utilities Commission (CPUC) to assess whether data centres result in cost shifts to other customers.
- In 2026, Texas, New Jersey and California enacted laws requiring data centres to pay for any new power infrastructure themselves, although they take different approaches to it.
- Texas insists developers pay in full, with hefty non-refundable deposits of $50,000 per megawatt of demand. New Jersey law now means data centre developers will be liable for 85% of the project costs, over ten years, whether they use the generated power or not. California’s new law requires the CPUC to assess reasonable costs to be borne by the developer.
- Georgia’s 2026 session saw a lot of proposed bills with similar intent to the above laws, but each failed to pass.
- Nevada has no data centre laws, either live or in the pipeline.
The rise of moratoria
In August 2026, the governor of Texas ordered a full audit of existing data centre projects before any new ones are approved. This bold move has resulted in a temporary, non-timebound pause. The open-ended delay could cost developers up to $8bn in lost revenues, according to Bloomberg analysts.
Other cities and counties are also pausing development applications, as part of the legal process. This affords them the time to draft new local laws.
New York is another high profile example. In July 2026, it issued a year long state-wide moratorium. This came in the form of an executive order by Governor Hochul, in an urgent response to an overwhelming 12GW of data centre power requests sitting in the queue of NYISO, the New York grid operator.
At a more local level, moratoria and outright bans are happening in pockets all over the country.
Of the studied cities, only Dallas, Texas, is directly affected. But Sparks may be next, through a local contagion effect. It’s near neighbour Reno, NV, has introduced a moratorium for 12 months, to run through to August 2027. Two other counties in Nevada have issued pauses, with one of them enforcing an outright ban.
The art of the possible
How facing down tornadoes becomes the most attractive option
Ultimately, data centre location decisions come down to: where is it possible? Where is the grid stable enough? Where is the political environment stable enough? Where are delays in start-up least likely to happen?
These are big questions, where the answers can change quickly. With local rules evolving, political risk is an increasing factor in location choice. And with climate change already showing in insurance claims data, we expect the topics of insurability, raising environmental standards and extreme weather target hardening to grow in prominence.